The Central Bank of Oman (CBO) launched a National Fintech Strategy and a new single entry portal for fintech companies, the , on 22 September 2026. The launch was a joint effort with the Financial Services Authority (FSA) and the Ministry of Finance’s Istidama programme, the country’s national programme for financial sustainability and financial sector development.
His Excellency Ahmed Jaafar Al Musalmi, governor of the Central Bank of Oman, said:
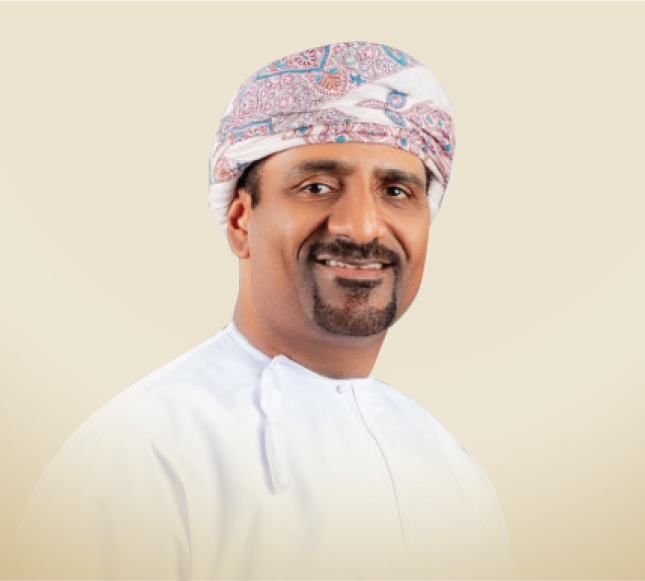
“Innovation and stability reinforce each other when grounded in sound governance and effective coordination.”

Mahmoud Abdullah Al Awaini, secretary-general of the Ministry of Finance, said,
“The strategy accelerates financial sector transformation aligned with the Istidama programme and Oman Vision 2040.”
Abdullah Salim Al-Salmi, chief executive of the Financial Services Authority, said,
“The strategy will enhance Oman’s attractiveness for local and international fintech investments through a supportive regulatory environment.”
Also, read Jordan’s Bank al Etihad Signs MoU to Set Up a Category 1 Bank in ADGM
What the Fintech Gate actually does
Where the strategy itself sets out policy priorities, the is a practical tool: a single portal for fintech companies and entrepreneurs entering the market. It provides guidance on which requirements actually apply to a given business, streamlines initial application procedures, connects applicants with ecosystem partners, and helps promising solutions advance towards direct engagement with regulators and exploration of market entry.
That single-entry-point model addresses a common complaint in , where a startup often has to work out for itself which of several regulators and requirements actually apply before it can even begin the licensing conversation.
The strategy’s stated priorities
The National Fintech Strategy names four priorities: improving financial inclusion, strengthening digital infrastructure and interoperability, supporting entrepreneurs and startups, and creating a regulatory environment that enables innovation while maintaining financial stability, cybersecurity and consumer protection. Ibtisam Ahmed Al Farouji, undersecretary of the Ministry of Commerce, framed the integration across regulators as reflecting “orientation toward developing an integrated investment experience for fintech sector participants.”
Why it matters
Oman’s fintech sector has drawn comparatively little coverage relative to the UAE, Saudi Arabia and Bahrain, its larger and more established GCC neighbours in this space. A national strategy paired with a single practical entry portal, rather than policy language alone, is a concrete signal that Oman is trying to compete for the same fintech investment and talent those markets have already attracted, rather than simply issuing an aspirational framework.
What’s next
Whether the Oman Fintech Gate actually reduces the time it takes a fintech company to secure Omani market entry, the practical test of whether this initiative works, is not yet measurable and is the detail worth tracking as the portal goes live.